
Adobe ADBE shares have risen 24.4% in the past three months, outperforming the broader Zacks Computer and Technology sector’s return of 8.1%. The outperformance can be attributed to stronger-than-expected operating momentum, accelerating AI monetization, expanding user engagement and Adobe’s decision to raise its fiscal 2026 outlook.
The company has been playing a catch-up role in the AI domain, not only against established players like Microsoft MSFT, Alphabet GOOGL and Salesforce CRM, but also from AI-native companies like OpenAI, Midjourney and Canva. Over the same time frame, Adobe shares have outperformed Alphabet’s 1.7% drop but lagged Microsoft and Salesforce appreciation of 41.8% and 58.2%, respectively. So, what should investors do with Adobe stock? Let’s find out.
ADBE Stock’s Price Performance
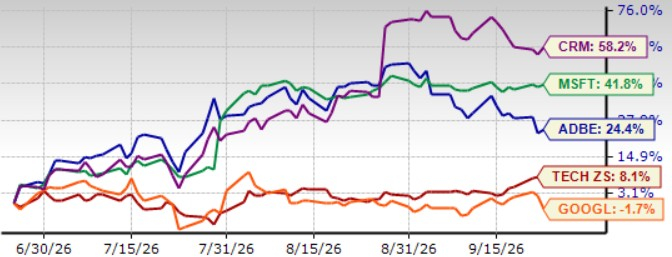
Image Source: Zacks Investment Research
Adobe Trades at a Discount
Adobe has a Value Score of B, which suggests the stock is trading at a discount.
In terms of forward 12-month price/earnings (P/E), Adobe shares are trading at 8.88X, lower than the broader sector’s 21.45X, Microsoft’s 23.99X, Alphabet’s 20.55X and Salesforce’s 14.05X.
ADBE Stock’s Valuation
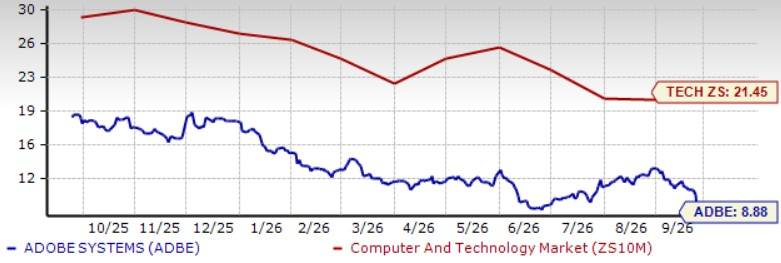
Image Source: Zacks Investment Research
Adobe’s Prospects Ride on Growing AI-Monetization
Adobe’s AI push is gaining traction. The company is beginning to demonstrate tangible monetization from its AI investments. AI-first ending ARR exceeded $650 million and increased more than 150% year over year in the third quarter of fiscal 2026. Firefly ending ARR across the Firefly App and Firefly credit packs jumped 40% sequentially, while customer adoption and usage of Firefly Enterprise continued to accelerate. These trends suggest that generative and agentic AI are increasingly becoming incremental revenue drivers rather than merely product enhancements.
Adobe surpassed one billion monthly active users across its businesses, with overall MAUs increasing more than 20% year over year. Creative freemium MAUs exceeded 100 million and grew more than 70%, while Acrobat and Express MAUs surpassed 900 million, increasing more than 25%. Acrobat AI Assistant MAUs also doubled sequentially. The expanding freemium funnel gives Adobe a larger base from which it can convert users into paid subscriptions and AI-credit customers.
Adobe’s largest opportunity remains integrating generative and agentic AI across Photoshop, Premiere, Illustrator and other Creative Cloud applications. The Creative Agent is being expanded across flagship applications, while Firefly now supports image, video, music, speech and sound-effects creation. Adobe is also integrating third-party models and intelligent model routing, giving customers greater choice without requiring them to leave Adobe workflows. Rising AI-credit consumption and Firefly ARR indicate growing willingness to pay for these capabilities.
Meanwhile, Adobe’s customer-experience business represents another important AI monetization opportunity. Adobe CX Enterprise combines Experience Platform, GenStudio, Experience Manager and agentic applications. CX Enterprise Coworker, which became generally available in June, already had more than 1,700 customers and early adopters. Adobe is also seeing more than 20% ARR growth across AEP & apps, GenStudio and AEM & agentic web apps, indicating healthy demand for its AI-driven marketing portfolio.
Adobe Faces Multiple Challenges
Adobe’s biggest challenge is proving that rapidly expanding AI engagement can translate into durable revenue growth. The company’s accelerated freemium strategy intentionally sacrifices some near-term ARR in exchange for faster user acquisition. ADBE acknowledged that the shift toward Firefly and other freemium experiences, together with the decision to defer previously planned Creative Cloud line optimizations, is lowering second-half ARR growth expectations from individual subscribers.
Intensifying competition is a headwind for Adobe. The AI transition requires significant ongoing investment. Adobe indicated that it intends to keep spending on models, cloud infrastructure, products and marketing to establish itself as a preferred AI platform. These investments are expected to restrain margin expansion if monetization takes longer than expected.
Adobe’s Earnings Estimate Revision Trend Steady
Adobe now expects fiscal 2026 revenues between $26.576 billion and $26.626 billion and non-GAAP earnings in the $24.45-$24.50 per share range.
The Zacks Consensus Estimate for fiscal 2026 earnings is currently pegged at $24.47 per share, up 8 cents over the past 30 days, indicating 16.86% growth from the figure reported in fiscal 2025. The consensus mark for fiscal 2026 revenues is currently pegged at $26.6 billion, suggesting 11.92% growth from the figure reported in fiscal 2025.
Adobe Inc. Price and Consensus

Adobe Inc. price-consensus-chart | Adobe Inc. Quote
Conclusion
Adobe’s improving AI monetization, expanding user base and growing adoption of Firefly, Acrobat AI and CX Enterprise strengthen its long-term growth prospects. The raised fiscal 2026 outlook and steady upward earnings estimate revisions also underscore healthy operating momentum. Moreover, ADBE’s discounted valuation compared with the broader technology sector and major peers offers some support following the stock’s recent rally.
However, Adobe still needs to demonstrate that rapid AI engagement and its expanding freemium user base can translate into sustained ARR growth. Intensifying competition from established technology players and AI-native platforms, along with elevated investments in AI models, infrastructure and marketing, could pressure profitability.
ADBE currently has a Zacks Rank #3 (Hold), which implies that investors should wait for a more favorable point to accumulate the stock. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers “Most Likely for Early Price Pops.”
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
Adobe Inc. (ADBE) : Free Stock Analysis Report
Microsoft Corporation (MSFT) : Free Stock Analysis Report
Salesforce, Inc. (CRM) : Free Stock Analysis Report
Alphabet Inc. (GOOGL) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.